Market Musings Blog

The Best Way to Save For College – or anything – That You Never Heard Of

A common college savings solution, 529 plans allow tax advantaged savings for college but only if the funds are used for education; and your money must be allocated among the funds allowed in the state’s plan, the account must pay fees to the state, and you must limit investment changes, etc. By now you are probably pretty familiar with the rules, but maybe you are less familiar with the mediocre performance at many college plans. Too, you need to keep an eye on the underlying funds – which have a habit of becoming more risky when markets are good – and can be changed by the state whenever a fund company’s contract doesn’t please the state. In short, these accounts have many pitfalls.

Call this the ‘Anti 529 Plan’. Tucked under a corner of the municipal bond market, you will find zero coupon bonds, which you buy at a deep discount, like the old government savings bonds. On maturity, the bonds mature to full par value. The difference between the purchase price and par is your yield.

Because the market prefers immediate cash flow, zero coupon bonds have higher than average yields, because all their cash flow comes at maturity. Since the bonds are municipals, your tax impact will be nothing, or very nearly nothing. Better yet, you can keep the bonds in your name, and if your child does not go to college, you can use the money yourself. No restrictions.

Zeros can be used to save for all kinds of things, but they work best for intermediate to long term goals, like college savings for a young child, or retirement savings.

There are two drawbacks to these bonds: they can be hard to find (you will need a broker to look for you, but a discount broker could do the job), and credit risk is a minor issue with some of these bonds. Stick to well rated issues in solid states, and you will be fine.

As a rough example of how these bonds work: You should be able to buy $50,000 worth of bonds due in fifteen years for a little north of $26,000. That equates to about a 4.4% tax free return every year. No mess, no fuss. Just salt them away, and you will find a pot of gold when you need it.

We usually advise that clients use this strategy in conjunction with something that offers higher returns, like stocks, but only if the runway is long. Last thing you need is for stocks to drop 20% just when you need to write a tuition check!
How to Get Rich, Pt II

In our first post on how to get rich, we counseled saving money. The point of this exercise is not only to accumulate a few bucks, but also to get into the habit of looking for places to save money. That will serve you well, all your life.

Here is our second secret:

Be Patient.

Yes, I know, it seems so… mundane. And as Americans, we are notably impatient.  But patience is much overlooked in the quest for wealth. Articles, books, advisers – they all focus on what to buy, only rarely what to sell, and never how to behave once you own what you bought.

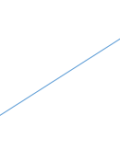
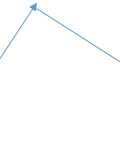
Ok, you have to start with a reasonable investment. You can’t buy a dud and be patient and expect great results. But what is wrong with buying a blue chip company or two and holding it for a long time? Basically what you want to do is turn the line on the right, which is how nearly all investments look in the short term, into the line on the left, which is how good investments look over time:

   arrow1                     arrow2         Even if you are not that ambitious, and all you buy is something with a 4% yield, patience pays off. A 4% investment will net you just shy of 50% more than you started with after ten years.

So: save money, and be patient. These are the simple secrets to getting rich.


How to Get Rich, Part I

This is a two part blog on how to get rich. It is two parts because there are only two things you need to know. This part is about the first of those things:

Save money.

You do not have to save a lot of money. You only have to get into the habit of saving money. Here are some ways to save money:

Buy your jeans at a thrift store. When you want something expensive, make a deal with yourself to give an amount equal to its price to charity. This seems like it is a way to spend more, but if you keep your promise to yourself, you probably will not buy that expensive thing. Shop for car insurance every few years. Shop for home insurance every few years. Audit your own phone bill. Every time I do this, I find that I am no longer using a service that I am paying for, or that there is a new, cheaper plan for what I am using. Vacation at home. Buy a cookbook and cook at home more often than you go out. Quit the gym and exercise at home with DVDs or just on your own. Invite a neighbor if you need moral support. Turn something you like to do into a sideline job; save the money. One nice thing about spending your time this way is – you won’t spend it shopping. Buy a French Press/cappuccino machine/burr grinder and make coffee at home/in your office.

Think of ten more things that apply to your life and try them too. Make a game out of saving, and you will begin to notice more money in your wallet every month.

Next post: the second secret to becoming rich.

Yellen Speaks, Market Listens

Today, March 19, Janet Yellen said she would raise interest rates sometime in 2015. The market heard, and interest rates rose. Rates were described in the media as “leaping”, “surging”, “rising sharply”. This day is a dream come true for all those strategists who started 2014 with bullish sentiments towards stocks and bearish sentiments towards bonds. But let’s see what today’s ‘enormous’ increase in rates really means.

First, long bonds, due in thirty years, closed today at the same yield as at the end of January. This yield, 3.64%, is well below the high for the year at 3.95%. At the other extreme, the one year note is at the same old January yield too. But in between! Oh my! The ten year closed at a yield of 2.76%, which means its price was a whole 0.7% lower than the day before! Disaster! And the five year with a yield of 1.69% – same deal! Catastrophe!

On this same day, the S&P 500 sank 0.6%. Somehow, though this decline was pretty competitive with the bad news from bonds, the media wasn’t impressed. No one really mentioned stocks.

The words used to remark on today’s market activity – or not, as the case may be – tell us that the consensus weighs in favor of stocks here in 2014. People want to believe stocks are going to be great again, like in 2013. This isn’t unlike those of us who are Yankees fans, pining for Derek Jeter. It’s tough to admit he’s aging. The bull market is aging, too. It might not retire, but the home runs are over for now. And while we are not nearly as bearish as most of our peers towards bonds, returns there will be at best singles or doubles. All in all, this year is shaping up as less rewarding, but more risky, than 2013.

When Should I Draw Social Security?

Until a few years ago, a retiree’s debate about when to draw Social Security revolved around age – usually 62 or “full retirement age”, somewhere between 65 and 67, or sometimes later if he didn’t need the money. However, Social Security rules are very complex, and someone discovered that there are all sorts of strategic possibilities for filing, including filing to collect a divorced spouse’s benefit, or a widow’s benefit, or even the “file and suspend” category which has one spouse collecting first on the other spouse’s benefit, then switching to her own. In short, there’s now a cottage industry formed around maximizing Social Security benefit payments.

If you thought this was something you could do yourself, put that out of your mind. You can’t possibly know all the rules. Did you know, for instance, that if you collect on your spouse’s benefit, and you are less than full retirement age, your spousal benefit will be reduced but may still exceed what you would get otherwise? And here’s a nifty trick. If you file and suspend at your full retirement age, and you still have young children in the house, your child can be entitled to half your benefit until their age 18!

We have reviewed multiple websites with information on filing strategies – some of which is incorrect.  By far the best way to handle your own situation is to make an appointment with your local Social Security Administration office with your spouse in attendance if applicable, and let them tell you how to handle filing. Their database can provide numbers that you might need for this exercise and otherwise cannot obtain, such as a deceased spouse’s benefit. You may find that with little effort you can have your cake and eat it too.