Market Musings Blog

Stay Safe Online

Good afternoon. We’re writing today because two of our clients were hacked within a week of each other, causing no small amount of disruption to their lives. This is a reminder about how to stay safe online.

  • Do not click links in emails, even when the sender appears familiar. Instead, verify the message independently by calling the sender or by visiting the relevant website directly.
  • Never engage with or reply to unexpected emails regarding charges, orders, inventories, or reports. If you receive an email detailing an order you did not place and want to check on it, find the company through Google and contact them directly to inquire.
  • Never respond to urgent messages, pop-ups, screen takeovers, or phone calls claiming to be from Microsoft, the IRS, a court, a state revenue department, etc.  Legitimate organizations generally will not demand immediate action, remote access to your computer, payment by gift card or wire, or sensitive information by email or phone. If you believe a matter may be legitimate, locate the organization’s official contact information through verified channels and call them directly.
  • Avoid using Zelle, PayPal, Venmo, or similar services at a stranger’s request. This is particularly important when someone claims a payment is needed to “stop fraud,” issue a refund, or protect your account. Refer the person to their bank or vendor to resolve it.
  • Use strong, unique passwords for every important account, especially your email and financial accounts. Reused or weak passwords can let someone who gains access to one account try to access others. Enable multi-factor authentication wherever available and change your password occasionally. This also includes using different passwords for social media accounts.
  • Protect your email account carefully. Your email password can be hijacked and used to change passwords on other of your accounts.
  • Keep your devices and home network secure. Use a password or screen lock on every computer and mobile device, including your router if you have one. Change your home Wi-Fi password periodically—especially after sharing it with a visitor.
  • Log out of websites and services when you are finished. Do not leave accounts signed in or leave devices unattended.
  • Never email documents or send messages containing sensitive financial information. That includes brokerage and bank account numbers, SS numbers, tax documents, etc.
  • Treat email as potentially public. If you would not be comfortable seeing your email on the front page of The New York Times, do not send it.
  • If you believe your computer or account has been compromised, immediately stop using it. Get a professional to wipe the drive.
  • Stay cautious and vigilant in your digital life. It’s the best way to prevent hacks these days, unfortunately. Cybercriminals often rely on urgency, fear, and confusion to persuade people to act before thinking.


Listen Up, Washington Residents: Estate Tax Changes in Your State

Washington state enacted substantial estate tax reforms effective July 1, 2025. The exclusion amount per estate increased from $2.193 million to $3 million, with future automatic adjustments for inflation. This change exempts more modest estates from state tax, alleviating liability for many families, especially those near the prior threshold.

However, estates that exceed this exemption now face much steeper tax rates—specifically, the top marginal rate rose sharply from 20% to 35% for taxable values above $9 million, giving Washington the highest top state estate tax rate nationwide.

Deductions for qualified family business and farm property were modestly expanded and eligibility broadened, aiming to boost intergenerational farm succession and family business preservation. While more estates are now exempt, higher net worth individuals with large estates might want to head to a favorite estate planning attorney for a fresh look at existing plans.

How To Download Your Gains/Losses Tax Information From Schwab:

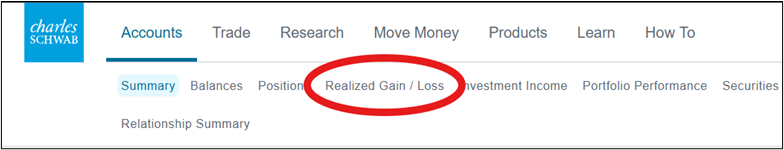
Once you are signed into your Schwab account, you’ll look for the link titled “Realized Gain/Loss,” located on the top navigation bar.


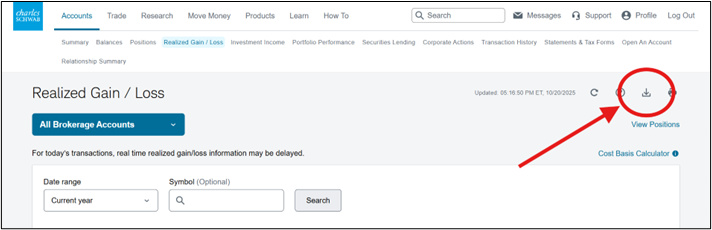
Once you’re on the Realized Gain/Loss page, you’ll see options to select from specific accounts, or setting specific date ranges. To download your Gain/Loss info, look for the download button on the top-right hand corner which will look like this:


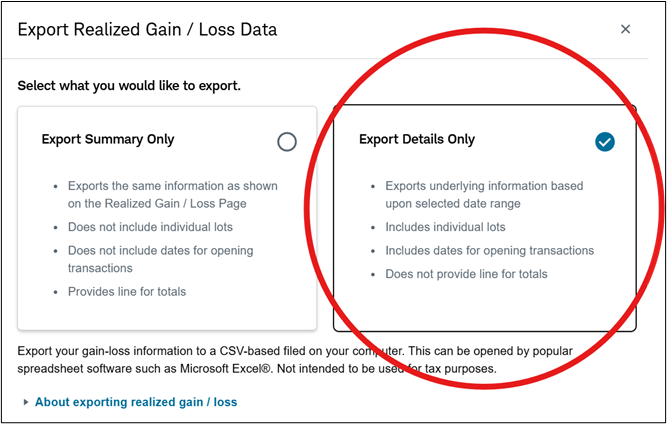
A window will pop-up and give you the option to select how you would like your information exported. Select the option to export details only.


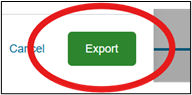
Then just simply tap the Export button!


It should automatically begin the download! Depending on your browser, the download should be found in your download’s folder. You can also open it immediately, right from the notification on your browser!

Private Equity in 401(k) Plans: Hazardous, or Helpful?

In early August, President Trump issued an executive order directing the Department of Labor to re-examine ERISA rules that have historically served to restrict the menu of investment options offered by retirement-plan sponsors. ERISA specifically prohibits only collectibles and certain precious metals, but concerns about liability have effectively eliminated alternative investments — including private equity, private credit and cryptocurrencies — in participant-directed retirement accounts.

On the other hand, institutional pension plans have been able to pursue alternatives as part of sophisticated diversification strategies. That fact has bolstered arguments that individual investors should have the same options. President Trump’s executive order seeks to do that by expanding safe-harbor provisions, allowing plan sponsors to continue to meet their fiduciary obligations while remaining largely protected from liability — even if alternative investments are included among plan options.

This article addresses the potential inclusion of private equity into 401(k) plans; other alternatives are outside our scope.

A Bit of History

Most of us have forgotten that “401(k)” refers to a section of the Revenue Act, signed into law in 1978. It allowed employees to defer taxes on compensation. As defined benefit pension plans became less viable due to rising costs and deteriorating actuarial outcomes, plan sponsors turned to offering 401(k)s.

As contributory plans proliferated, employers were gradually relieved of responsibility for their employees’ retirement savings. Whether this result was good or bad is debatable, but two things are evident: 401(k)s are not managed in the same way as sophisticated pension funds. Nor do 401(k)s provide the same mostly reliable “peace of mind” benefit that accompanies a lifetime pension.

What’s More Important Than Returns

The reliability of large pension funds does not reside in superior returns. Over the five years ending 2023, Vanguard reports that annual “personal” returns on 401(k) accounts it administers came to 8.9%. Meanwhile, Milliman reports that large pension funds returned 6.0% per year over the same timeframe. In other words, the average Joe performed much better than the average pension fund.

But returns are one thing, and funded status is another. Pensions are particularly flush at the moment, sitting just shy of 100% funded. Meanwhile, 401(k) balances do not come close to replicating the lifetime income of a defined benefit pension. Furthermore, the returns accruing to 401(k) accounts are fueled by large dollops of high-performing technology companies. The S&P 500 itself is about 35% “invested” in technology.

Pension funds are all about achieving results within the guardrails of reasonable risk. You’ll never catch a defined benefit plan invested 35% in technology. In fact, stock exposure at large pension funds has fallen dramatically over the last several years — in favor of alternative assets including private equity.

Stock Market Shift

This phenomenon of pension funds shifting toward alternative assets is partially due to a dramatic decline in the number of U.S. public companies, particularly since 1996. Today, there are fewer than 4,000 publicly traded companies on our exchanges, a drop driven by mergers, de-listings, regulations and reporting requirements layered onto public firms.

The structure of the stock market also has shifted, with large companies dominating returns while small companies remain sheltered in private hands. This phenomenon has even begun to shift long-term asset class returns:

  • From 1928 to 2024, publicly traded small-cap stocks delivered an average annual return of 11.7%, outperforming the S&P 500’s 9.94%.
  • However, between 1975 and 2024, the performance gap between small caps and the S&P 500 nearly vanished.
  • More recently, from 2015 to 2024, the trend has reversed: The S&P 500 averaged 12.98% annually, while small-cap stocks lagged significantly at just 5.21%.

Where Has the Small-Cap Premium Gone?

It has likely migrated to private-equity returns. Notably:

  • CalPers reports that its private equity allocation has returned over 11% since inception through 2024.
  • Cambridge Associates reports a 10-year average annual return of 14.89% for its private equity index through March 2025. This figure is consistent with the historical performance advantage that small-cap stocks had over large-cap (S&P 500) stocks.

These numbers raise the legitimate concern that individual investors are excluded from increasingly attractive opportunities that are no longer available in the public markets. Beyond returns, diversification is also a valid concern: Retirement plan participants are relegated to an ever-shrinking subset of investments that grows ever more concentrated by the day.

Longtime Deterrents May Dissipate

True, private equity vehicles are renowned for illiquidity and expensive management fees. But we believe that expanding the market for all alternatives will lead to lower fees and increased liquidity as participants pursue — and eventually demand — these benefits in exchange for what could be significantly broader market access.

Furthermore, because fiduciaries are expected to act with care, transparency and disclosure around alternative investments are likely to increase over time.

Not only does the inclusion of private equity in 401(k) plans confer potential benefits to buyers, it also solves two problems for private companies themselves: Increased access to capital and liquidity for early shareholders. Both are significant challenges that have been exacerbated by government regulations, interest rate swings, and other factors having nothing to do with the validity of business plans. Small businesses are the lifeblood of the U.S. economy, and our institutions should be built to support their success.

While critics may decry presenting an asset class historically reserved for the well-heeled as a free-choice option for less sophisticated investors, evidence shows that participants are increasingly rational in their approach to investing and markets. During stock price declines, investors not only refrain from selling, but they’ll tend to add to stocks, and the bad habit of ceasing contributions has eased.

Exploring an expanded slate of investment vehicles, if ushered in with care by plan sponsors, could enhance returns and diversification for participants, as well as boost transparency, capital formation and liquidity for private equity — an increasingly important segment of our economy.

This article was originally published by Rethinking65.
 

How to Optimize the Redemption of US Treasury iBonds

Treasury iBonds grew quite popular after inflation in the US spiked a few years ago. These bonds pay interest at rates approximating the Consumer Price Index, so high single-digit returns were not unusual. But rates have since declined, and investors may want to move on to greener pastures.

Redeeming US Treasury iBonds, especially if you are seeking to maximize returns, involves careful timing and a knowledge of the rules. Here’s a helpful guide:

  1. Hold for at Least 1 Year
  • iBonds cannot be redeemed before 12 months from the date of purchase.
  • Exception: There are emergency federal provisions, but in most cases, you must wait a year.
  1. Avoid the 3-Month interest penalty
  • If you redeem within five years, you forfeit the last three months’ interest.
  • To minimize the penalty, plan redemption timing so that the three months lost are at a lower interest rate, by waiting until your rate declines (see #4).
  1. Maximize final interest crediting
  • Interest is credited monthly but paid when you redeem.
  • Redeem shortly after the interest is credited for a month:
    • Best day to redeem: Early in the month, right after crediting occurs for the previous month
  1. If you must redeem within five years, understand rate change timing
  • Since iBond rates adjust every six months based on your bond’s issue date, check for that date and current rates.
  • Strategy: Wait at least three months into a lower rate period: You’ll then forfeit only lower-rate months when incurring the penalty, locking in all of the higher-rate months.
  • Use tools like EyeBonds.info or TreasuryDirect’s calculator to model forward-looking scenarios based on variable rates.
  1. Use the right redemption channel
  • Electronic bonds: Redeem directly via your TreasuryDirect account; funds are typically credited in 1–2 business days.
  • Paper bonds: Can be cashed at most local banks or credit unions (check current policies) for faster access. You do not need to convert paper bonds to electronic format to redeem.
  • For complex requests (trust, estate, etc.), or if your bank can’t process, use FS Form 1522 and mail to the indicated Treasury address.
  1. Tax Considerations
  • Interest from iBonds is subject to federal income tax but exempt from state and local taxes.
  • You can defer taxes until redemption, but must report all interest in the year you cash the bond or at final maturity (30 years).
  • If you are redeeming to use the proceeds for qualified education expenses, some or all interest may be tax-free.


Example

Suppose your bond’s high rate period ends April 2025 and a new, lower rate applies starting May 2025. Redeem in August 2025: the penalty forfeits May–July’s lower-rate months, while all higher-rate interest is secured.

Summary:

  • Wait one year after issuance, ideally five, for no penalty
  • Redeem after at least 3 months in a lower rate period if you are in a penalty period
  • Do it early in the month
  • Use correct redemption channel
  • Track and plan for taxes